Why Can't Hyperliquid's HIP-4 Prediction Market Catch Up to Polymarket?
 Tapbit Wire
Data as of October 5, 2026. Prices, staking, order books, and trades come from the Hyperliquid API; per-market volume comes from the node trade archive published by Liquidiction; Kalshi and Polymarket volume comes from The Block. Charts are identical to the English version, see above.
Summary
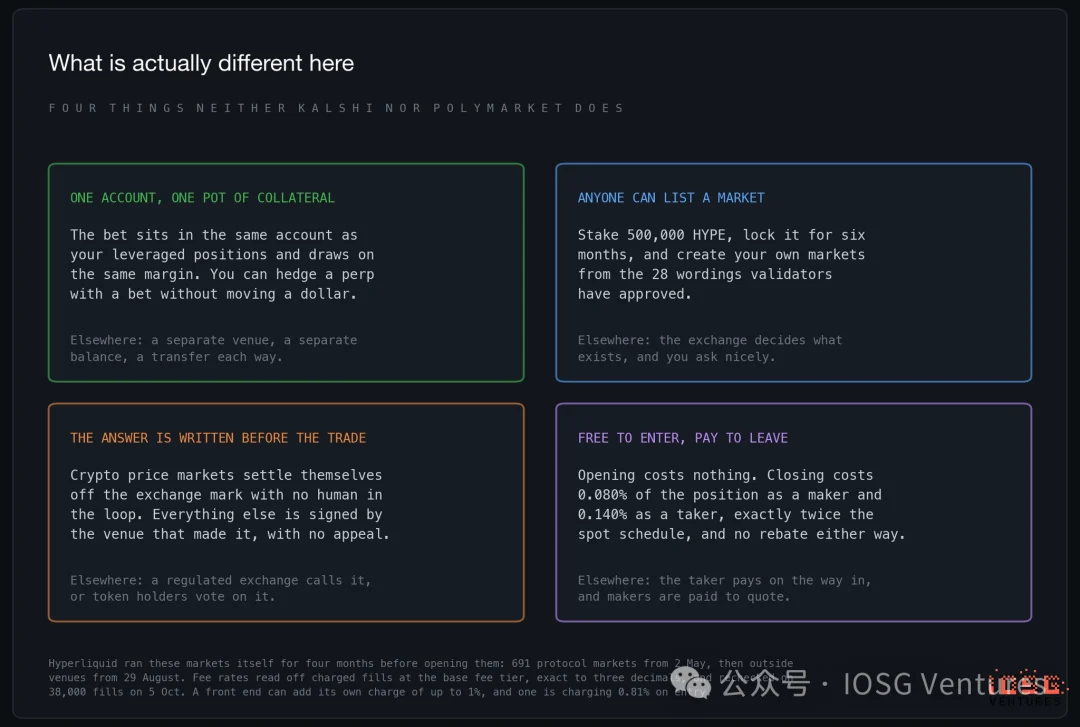
The thing HIP-4 most resembles is not Polymarket, but an options ticket sitting next to your perpetual position. Yes shares live in the same account as your leveraged position, use the same margin, and trade on the same matching engine, so a bet and the position it's meant to hedge are always on the same interface. Three other points also set it apart: anyone who stakes 500,000 HYPE can open a market; settlement conditions are locked into a template before the first trade; entry is free, exit costs roughly one-tenth of a percent — the exact reverse of how Kalshi and Polymarket charge.
For the first four months, only Hyperliquid itself was running. When it launched on May 2, 2026, all markets were operated directly by the protocol — 691 in total — and it wasn't until August 29 that it opened to external venues. Since then, three have posted stake, and there is still no fourth.
Whether you can see it depends on where you are. Prediction markets have a separate page, app.hyperliquid.xyz/outcomes, and the frontend decides by region whether to include it in the trading list alongside perpetuals and spot. Accessing from a Korean network, you can see this tab in the market list; on the network we tested with, it's missing from both the list and the menu, but the page itself still opens and trades. Hyperliquid restricts frontend access in several countries — an entry you can't see may be visible to someone two time zones away.
From May to now, HIP-4 has cumulatively traded $317 million — Kalshi does that much in under four hours. In September, for every $1,000 Kalshi and Polymarket traded, HIP-4 traded roughly 70 cents.
The design is its best part; the problem is scale. More than a quarter of all HIP-4 volume ever comes from the already-finished World Cup. The daily Bitcoin market that carried the first four months is down 93% from its May peak. New venues pulled September back to $51 million, level with July, and the venue contributing the most is paying traders roughly 0.6 cents for every dollar it trades. October has started even slower, averaging about $1.25 million a day. Fees across the whole market run about $1,300 a day — less than half the interest a single venue earns just by leaving its stake idle.
I. Product Design: Four Differences from Kalshi and Polymarket
Backing out the fee rate from trades that were actually charged, by base tier:
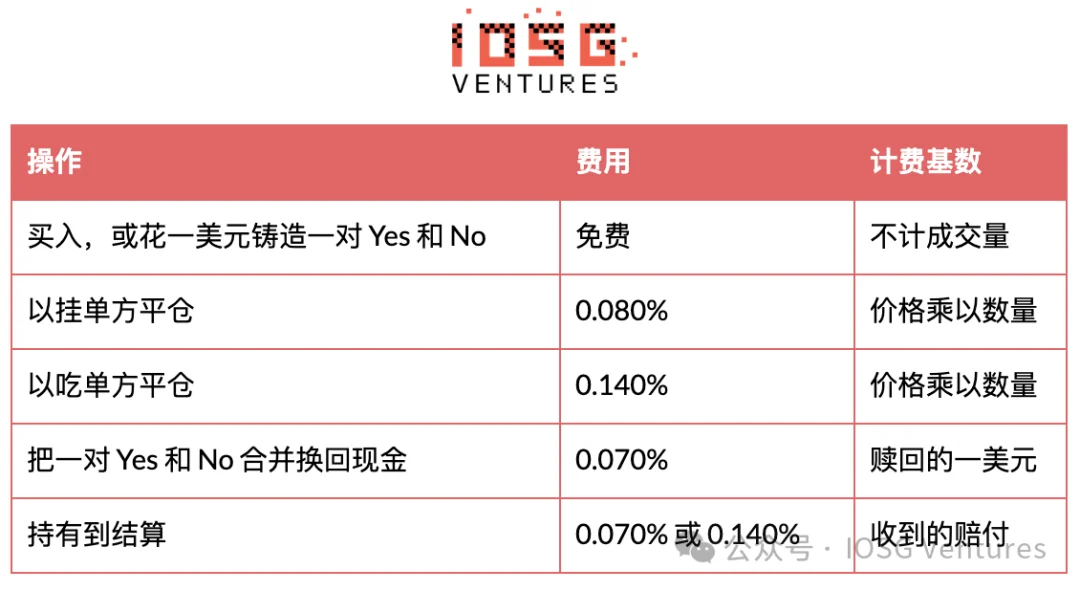
This is exactly double the spot rate: spot base tier is 0.070% taker, 0.040% maker. One side doubled, the other zeroed — a round trip costs the same as spot, just collected entirely on exit. Common discounts multiply simply: a 4% referral discount turns 0.140% into 0.1344%, and stacking a 10% staking discount gives 0.12096% — every trade we checked matched to the cent. There is no maker rebate, the one place market makers are worse off here than anywhere else on the exchange.
No venue has yet raised its fee coefficient above the default, so venue revenue is carved out of the protocol fee, not added on top. The only fee you might hit on entry comes from the frontend app: under spot rules, builder fees are capped at 1%, and one app charges 0.81% on entry — roughly six times the protocol's exit fee.
Settlement deserves a closer look, because that's where the venue's risk lives. Polymarket relies on UMA token holders voting to adjudicate, which earlier this year turned a $375 million Microstrategy market into a bitter fight. Kalshi, as a regulated exchange, adjudicates itself, with regulators above it. HIP-4 splits the matter: crypto price markets read the exchange mark price at the agreed minute and settle automatically; every other market is settled by the signature of whoever opened it — no dispute period, and no one can sign on their behalf.
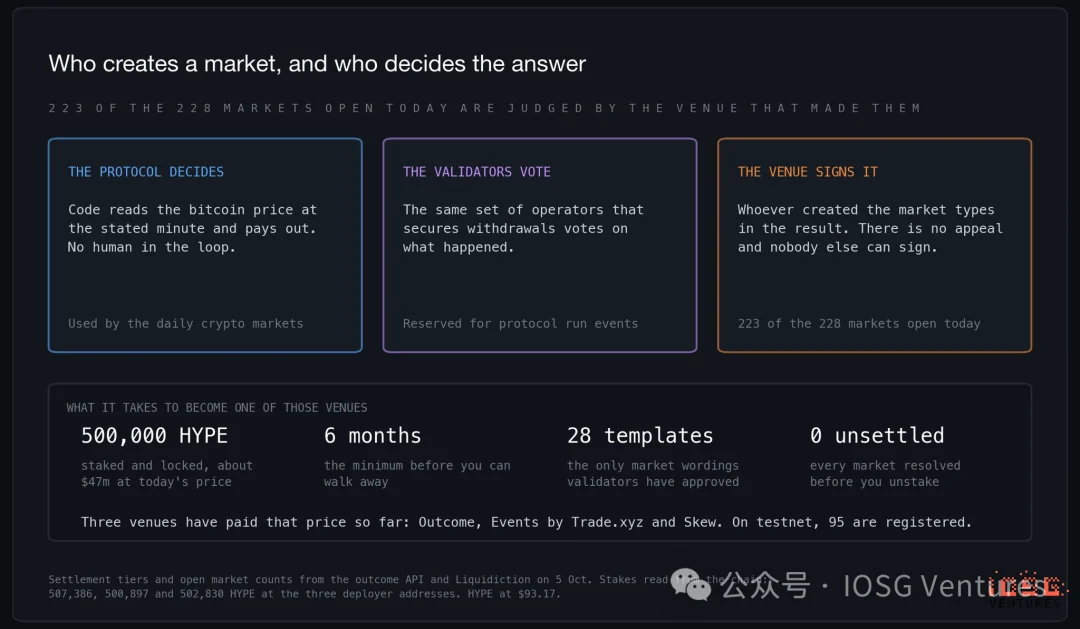
Of the 228 markets open today, 223 fall into the latter category. The constraint is money and time, not procedure. As long as a venue has unsettled markets, its stake stays locked; it can't be withdrawn for six months; and only wording pre-approved by validators can be used. That wording is deliberately long and pedantic — the "company IPO" template, for instance, lists a full page of conditions on what even counts as a listing. Rules written before trading beats arguing afterward. Handing the pen to a named party with no appeal channel is indeed worse than having a procedure — but only if that procedure itself doesn't break down.
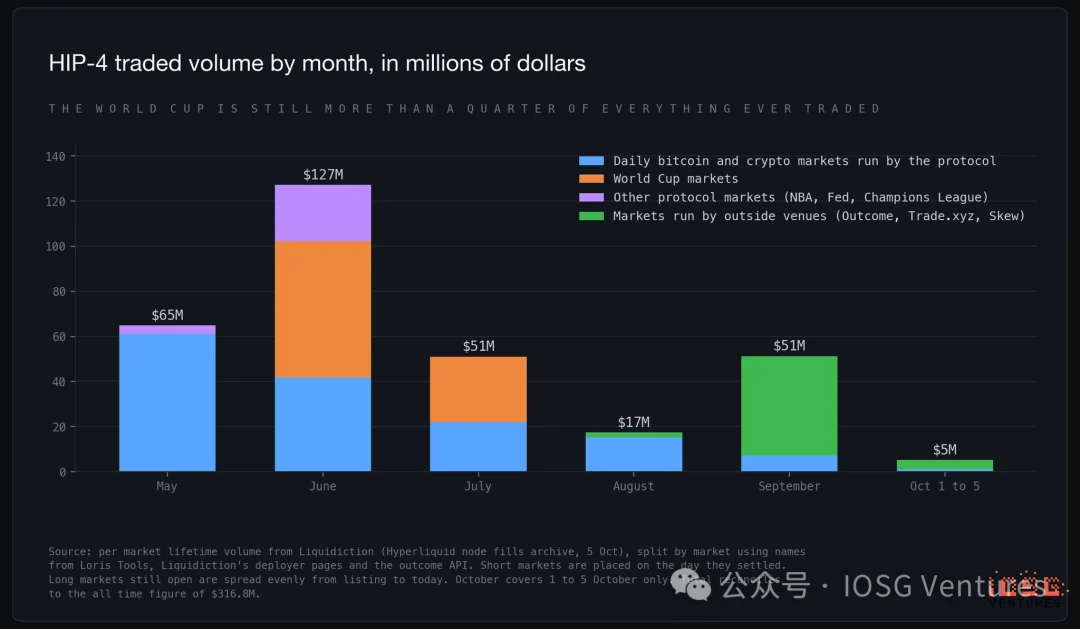
June was the peak, and the reason was the World Cup. Football markets alone traded $89.5 million, 28% of HIP-4's cumulative volume. Once the World Cup ended, volume fell more than 80% in two months. September recovered to $51 million, with the entire rebound coming from external venues; the first five days of October traded $5 million.
Beneath these events, the protocol has run the same market every day since May: will Bitcoin be above a certain price at six tomorrow morning. This is probably the most Hyperliquid-flavored product, and it fell for four straight months before bottoming out.
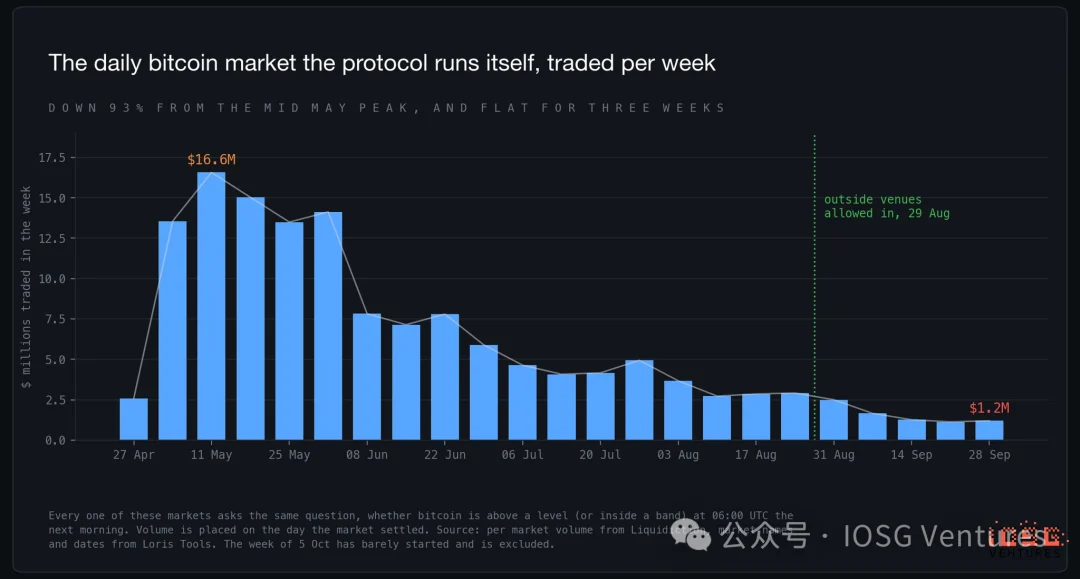
The week of May 11 traded $16.6 million; the week of September 28 traded only $1.2 million, and the two weeks before were about the same. Ask the same question every day and fewer people listen, until almost no one is left before it stops. Whatever HIP-4 becomes, it won't be this.
II. Five Weeks of Open Deployment:
Subsidy-Fueled Volume and Duplicate Listings
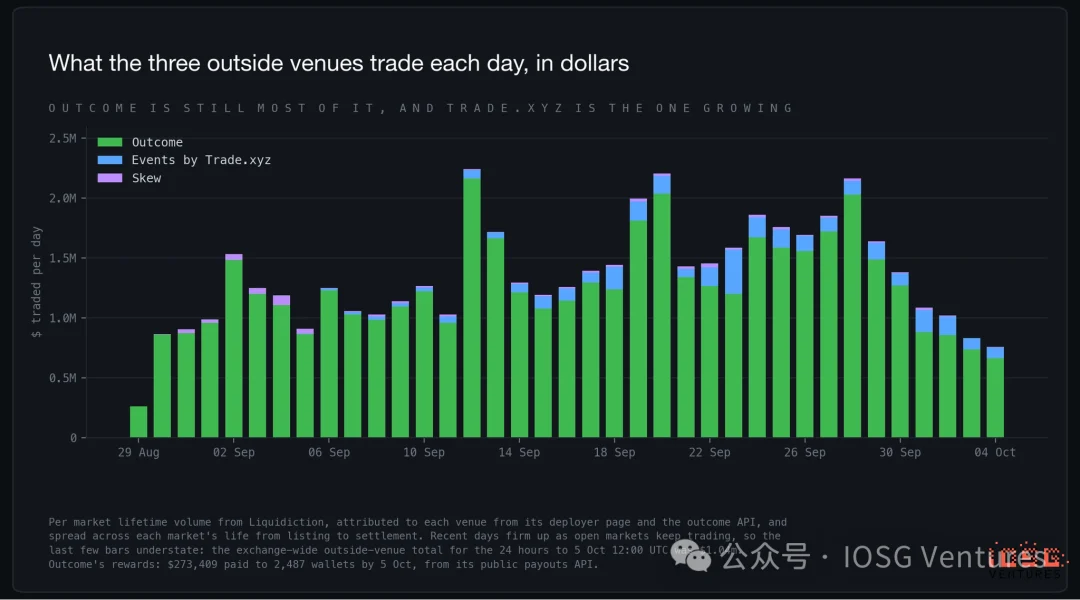
Outcome was the first to go live on August 29. Skew registered markets the next day and has barely traded since. Events, under Trade.xyz, registered on September 5 and opened to the public on the 10th. Across all of HIP-4, on the most recent day Outcome accounts for 68%, Trade.xyz 21%, protocol-operated markets 10%, and the rest is Skew. Counting only external venues, Outcome has taken 92% since August 29, while Trade.xyz has grown from zero to nearly a quarter on the most recent day. Its market selection is the most opinionated: binary contracts betting on its own stock and commodity perpetual prices, the NFL, and the exchange's only questions on whether Anthropic and OpenAI can list before their deadlines.
This volume needs to be discounted. Outcome has a $1 million rewards program that pays makers and traders per market, per day, but only for orders carrying its own app code. As of October 5, it has paid $273,409 to 2,487 wallets — about $7,400 a day, roughly 0.6% of Outcome's total volume, four times the cost of a round trip. A quarter of the budget is already spent, and daily payouts show no sign of slowing. External venues traded $1–2 million a day in September, busiest on weekends; by October that fell back to around $1 million a day, while the rewards keep flowing.
Open listing has also produced the first duplicate markets. Both Outcome and Trade.xyz listed the Fed's October meeting, and over the past seven days Outcome traded $354,000 there versus $90 on Trade.xyz. Both also listed a set of questions on Anthropic's first-day market cap, and neither side traded much. Anyone can list a question, which means two venues can list the same question, and their order books won't merge. Volume flows to the one paying subsidies.
Trading content is tilting toward sports. Over the past 30 days, football, American football, and esports made up 45% of volume, crypto price questions 42%, stocks and commodities 7%, and the Fed 6%. Open interest is even more skewed: two-thirds of at-risk capital sits on sports, mostly season-long markets like the Premier League, Champions League, and NFL champions, while crypto prices account for only 17%.
The available templates are growing faster than the venues. Validators have approved 28 templates, up from 18 in mid-September, adding spreads and over/unders, the Ballon d'Or, head-to-head matchups between two AI models on a leaderboard, and first-day market cap for company listings. The next network upgrade will double each venue's cap to 200 concurrent markets and 1,000 new ones per day. The testnet already has 95 registered deployers; mainnet still has three.
III. Order Source: Seven in Ten Flows Through Outcome
For a frontend app to place orders on your behalf, you authorize a separate signing key, and that key is named after the app. So a wallet registered on outcome.xyz permanently carries a tag like Outcome-9d3c74de, publicly visible to anyone. The exchange's own mobile login works the same way, showing as Mobile QR; the desktop signs every step with your own key and leaves no tag. We only looked at Outcome, because it accounts for about 90% of external venue volume and only its answer carries weight.
About 70% of volume comes from wallets registered on outcome.xyz, about a fifth from wallets with no tag at all, and a tenth from scripts and third-party tools that named their own keys. The larger the scale, the higher Outcome's share: three-quarters of the amount among the top 20 wallets, about half among the rest. This is exactly what a rewards program produces: it only rewards orders routed through Outcome's code, and the market makers collecting rewards happen to be the largest wallets.
This method has limits. A tag only means the wallet once registered through an app, not that any particular trade was routed by it. And the untagged fifth can't be treated as users of the exchange's official page: most of them quote both sides across many order books simultaneously — scripts signing with their own keys. The sample is 121 wallets drawn from recent trades on the 60 most active order books, weighted by 48-hour volume, naturally biased toward market makers. Fees don't answer the question either. Under 1% of the amount in the sample paid a builder fee — nine dollars over two days — while Outcome's own code charges nothing, and a free-routing app looks identical to no app at all.
IV. Benchmarking Against Kalshi and Polymarket: A Gap of Roughly 1,400x, and Still Widening
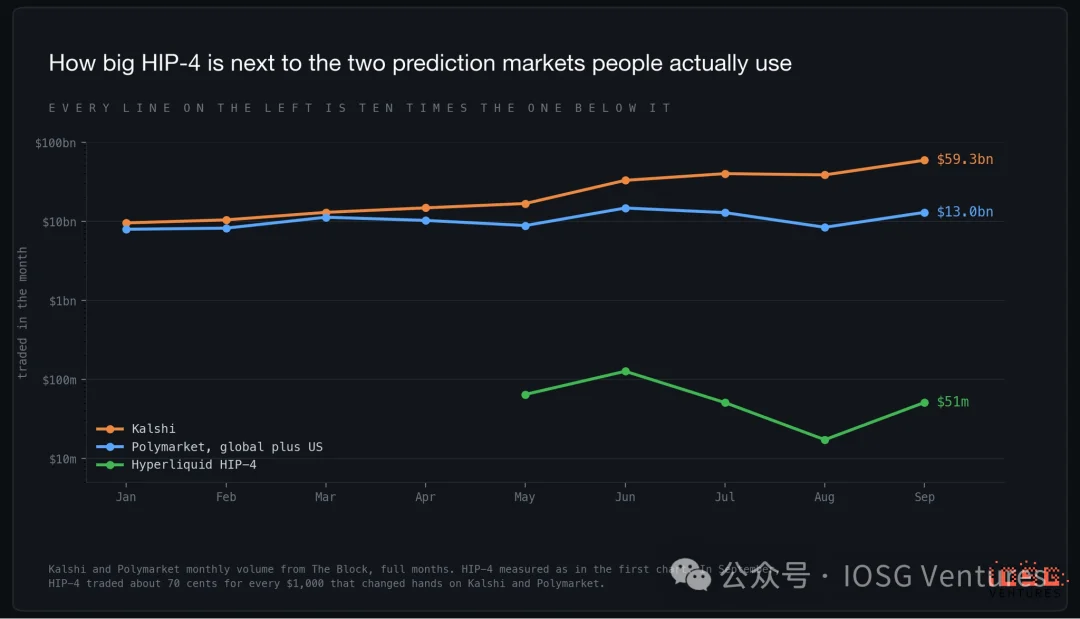
The gap is roughly 1,400x, and in dollar terms it's still widening, even as HIP-4 itself grows. Kalshi traded $59.3 billion in September, up $20.6 billion from August. Polymarket, including its US business, traded $13 billion, with the bulk now in the US app. HIP-4 did $51 million.
The incumbents' edge isn't in market design; they win on the two things that actually drive volume. One is events people care about — thousands of them, listable within hours of the news breaking. The other is distribution: apps, brands, sports audiences, and in Kalshi's case a compliant wrapper that US brokers can plug into directly. HIP-4 holds 28 templates, three venues, and a user base that was already doing perpetuals.
The incumbents are also starting to walk toward Hyperliquid. In early September, Polymarket launched perpetuals for users outside the US — 67 markets covering crypto, stocks, indices, and commodities, with leverage up to 20x. Putting bets and leveraged positions under one roof was HIP-4's exclusive. Now it's a feature race, and Polymarket entered holding the events.
V. The Economics: Market-Wide Fees Are Less Than Half a Single Venue's Staking Yield
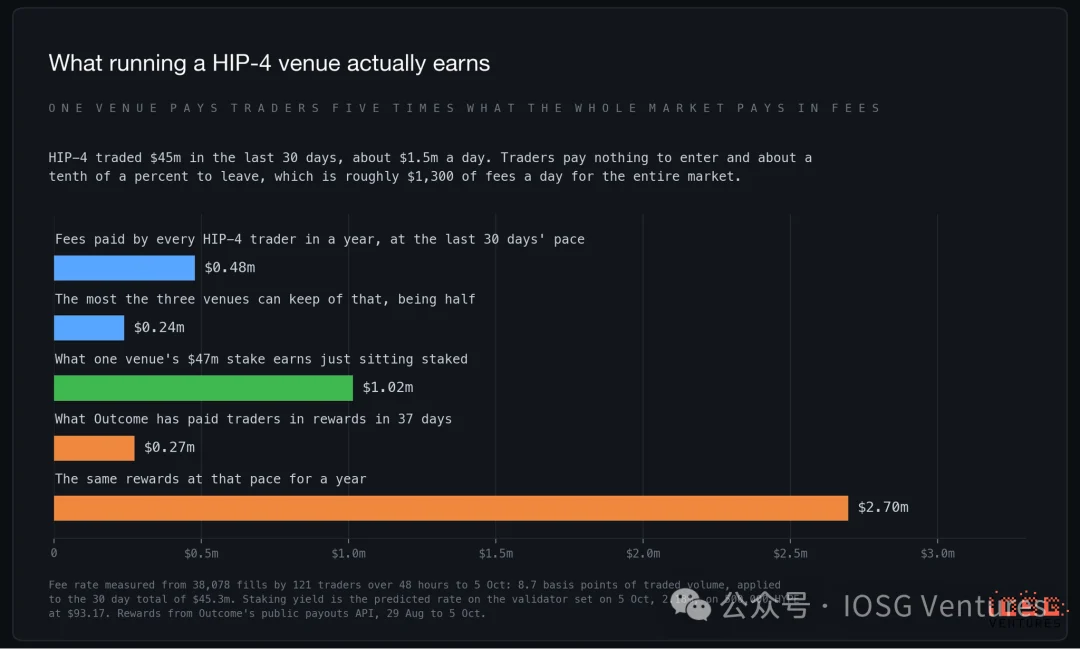
At the pace of the past 30 days, all HIP-4 traders combined pay about $480,000 in fees a year. Venues take at most half, split three ways. The stake a venue must lock to enter earns $1 million a year just sitting still; and the highest-volume venue is paying out rewards at $2.7 million a year to buy that volume.
By these numbers, no venue is running a business. They're buying an option, and the option has value: Hyperliquid says deployers can raise their own fee rates later, volume can grow to support fees, and the sector's private-market comparables are valued at $22 billion and $21 billion, with Kalshi reportedly in talks at $40 billion. But it's still an option, and the carrying cost is a $47 million stake that expires worthless if the volume never comes.
VI. Conclusion: Leading Design, Market Not Yet Arrived
The blocks are well built; the market hasn't come.
On the dimensions an engineer would pick, Hyperliquid has built the better product: one account, one pool of margin, a bet and the position it hedges on the same interface; settlement terms written into a template before the first trade; Yes and No on the same question sharing an order book, so liquidity isn't split in two. Nothing in the past five months suggests design is the bottleneck.
The strongest argument for it is that you never have to leave. Margin, hedging, and betting are all in one account — for a desk already doing perpetuals on Hyperliquid, adding a prediction position is a click, no switching platforms, no new balances, no transfers back and forth. Whatever the outcome against Kalshi, that has value, and it's why this will persist at some scale even if it never becomes a business. But it's less unique than it was in August: Polymarket now sells leverage next to its bets, and it started from the side that has users.
It's not deep enough yet. Across the 25 most active order books, the median bid-ask spread is 0.29 cents, with about $4,700 resting within a cent of the best ask. A $1,000 market buy fills only a few basis points above the best ask; a $10,000 buy pays 2% to 3% more, and on four or five of those 25 order books it can't be filled at all against visible quotes. Retail-sized trades work fine here; large money doesn't. Market makers keep re-quoting, and patient limit orders will do better than these numbers, but an order book this thin is exactly what a five-month-old market looks like.
It also has little to trade. Prediction market volume is made of topics, and topics come either from an editorial team listing hundreds of events a week or from a sports calendar. HIP-4 has 28 approved wordings, three venues each staking $47 million to use them, and two of them are already listing the same questions. Kalshi can open a market on a news story in an afternoon.
The user base is also specifically wrong. Each address trades eight times a day — that's a desk, not a betting public. If the goal is a capped-payout tool for crypto traders, that's fine; it's what this design does best. If the goal is the crowd Kalshi and Polymarket are fighting over, it doesn't work — and two-thirds of at-risk capital sitting on season-long football markets shows the venues are still pushing in that direction.
The most likely path is the plain one. HIP-4 will remain a feature of Hyperliquid, earning pocket change, its value being that perpetual traders don't have to open an account elsewhere. That's worth doing, but not worth valuing as a prediction-market business.