Quantitative trader confronts the 40 billion Kalshi empire, tearing down the veil of trading volume fraud
 Tapbit Wire
Trouble Caused by a Retort
The day before yesterday, crypto KOL and head of the Kalshi Crypto market segment, IcoBeast, posted a picture on Twitter with the caption: "Everyone, is 96.7% a lot?"
This figure came from a chart showing the market share of prediction markets compiled by Artemis. Kalshi occupied the vast majority of the area, while Polymarket was squeezed above. Beni replied below, stating that three-quarters of the volume was fabricated, making it easy to achieve this share.
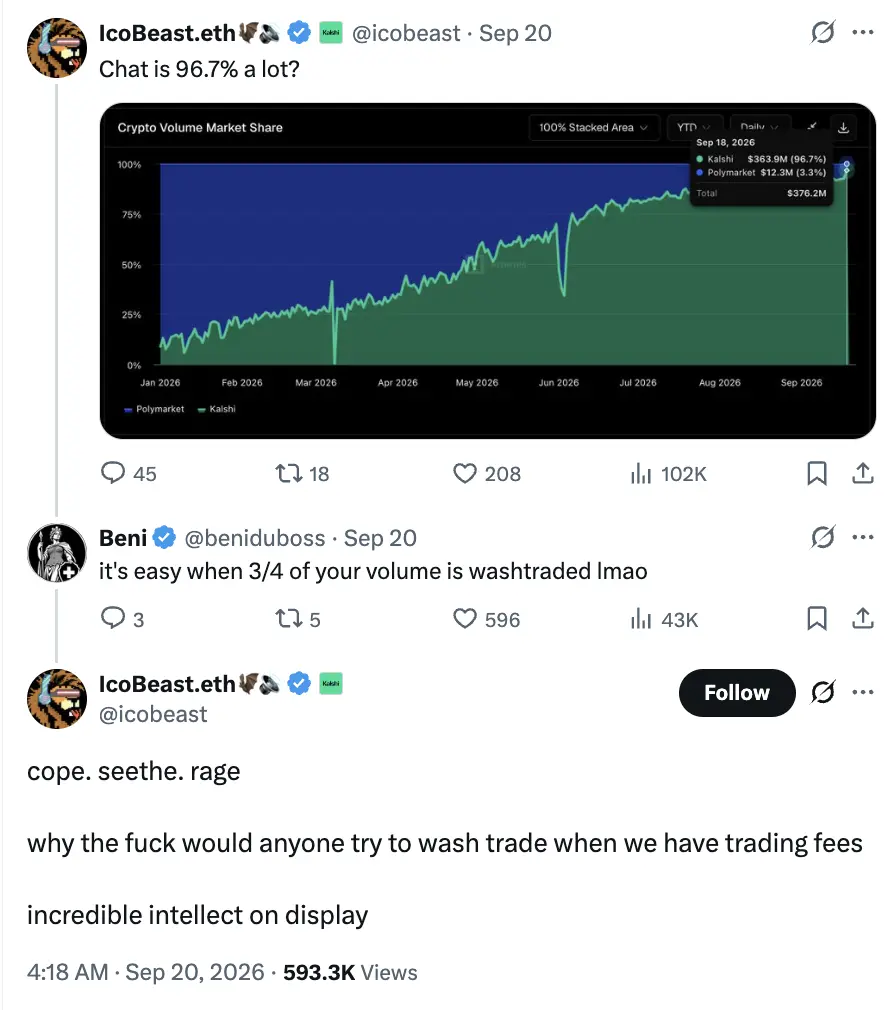
Next, IcoBeast provided a rebuttal that would later be repeatedly cited: "We collect trading fees, who the hell would still fabricate volume?" He also took a jab at the other person's intelligence.
Initially, Beni regarded him as a KOL promoting Kalshi for money and advised him to think it through and delete the tweet. IcoBeast retorted that he worked at Kalshi, had built the company's crypto market business from scratch over the past year, and knew that this volume was real. He then returned the phrase "Take a few minutes to think it through before deleting the post" back to Beni.
This might be the tweet IcoBeast regretted the most in his career, as he angered someone he shouldn't have.
Beni immediately posted a lengthy reply. The first rebuttal targeted the trading fees: In Kalshi's perpetual contract rebate program, eligible members are allowed to pay 0.3 basis points when taking orders and net receive 0.3 basis points when their limit orders are filled. Assuming a nominal amount of $1 million is traded between two members, the taker pays $30, and the maker receives $30, resulting in a total trading platform fee of zero.
Where did the "platform fees" that IcoBeast mentioned go?
Subsequently, Beni posted the page for the ETH perpetual contract: a 24-hour trading volume of $538.6 million, with an open interest of only $3.1 million. The trading amount for that day was equivalent to about 174 times the existing positions. He then found the repeatedly appearing $5,500 orders and publicly accused these fixed amount trades of creating volume.
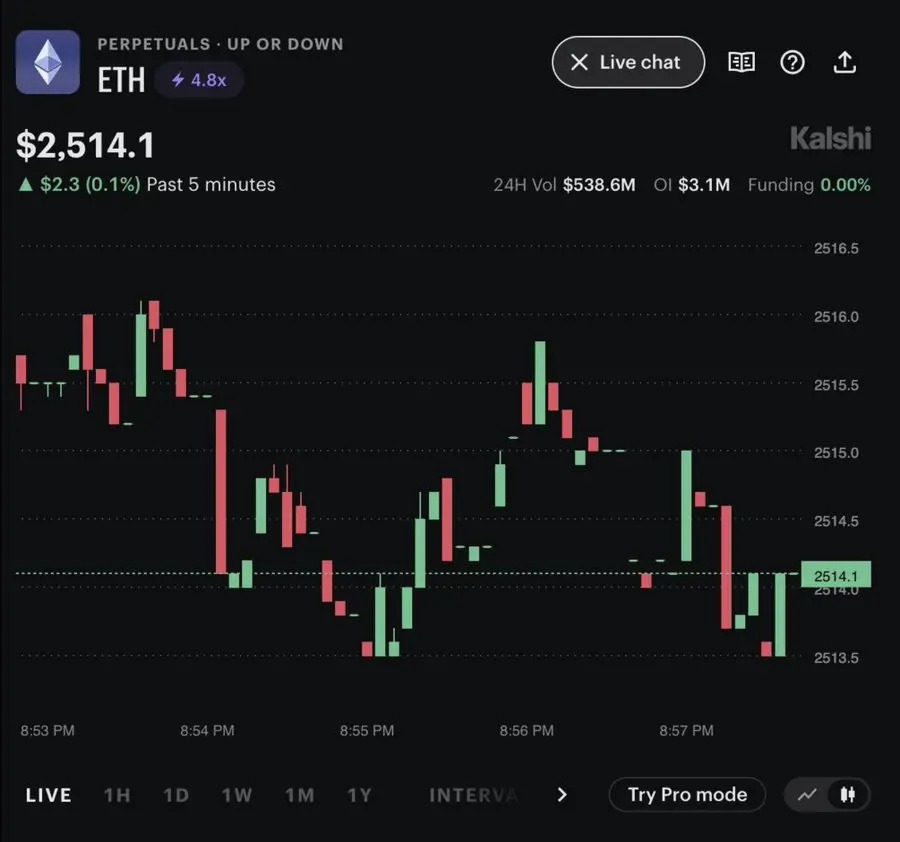
IcoBeast later added an important distinction: he initially presented the prediction market share, while Beni discussed rebates and open interest related to perpetual contracts. The prediction market does not have the 0.3 basis points rebate that Beni mentioned.
The problem is that IcoBeast's clarification only addressed the prediction market business and did not respond to the volume fabrication in the contract market. Beni seized on this point and continued to attack, with Kalshi needing to explain more and more.
Genius Trader
Beni's sensitivity to orders and fees stems from his work experience.
In a podcast interview, Beni recalled that he first encountered Bitcoin to play poker online. Later, his poker friends began making money by buying and selling cryptocurrencies, and he entered the crypto market. After losing money trading contracts, he turned to arbitrage across trading platforms and gradually studied order books and trading mechanisms.
In the early days of trading on Cryptopia, he would monitor the small tokens' deposits on the trading platform. When someone transferred coins in, there was a possibility of selling afterward; he would place buy orders at lower prices, waiting for the other party to break through the thin order book. To capture such opportunities, he used a block explorer to feed data from different websites into spreadsheets and alert systems.
Later, he worked with investors to run market-making bots in the Monero market on TradeOgre. The initial logic was simple: reference prices from other markets, add a spread sufficient to cover fees, and quote on both sides. As his experience grew, he adjusted the quoting range and margin based on large deposits. In his account, this business once accounted for about 65% to 70% of the trading volume in that trading platform's Monero market.
During Ethereum's "The Merge" upgrade, Beni observed 43 ETH contract markets simultaneously and found that the price on one contract platform spiked about 2% every 26 minutes before dropping back. He and his friends traded around this pattern for about 18 hours until the opportunity disappeared.
This is the opponent IcoBeast attracted: a master looking for market inefficiencies.
Beni's friend, another quantitative trader named Octopus, later published a working paper that visualized the accusations against Kalshi into charts.
Fixed Trading Volume
This research collected about 4.1 million public trades of Kalshi's perpetual contracts from September 5 to 18, with a nominal trading amount of about $11.486 billion, and compared it to about 408 million trades on Binance, Bybit, and Hyperliquid during the same period.
The easiest finding to understand is that the trading volume is abnormally concentrated around several dollar amounts.
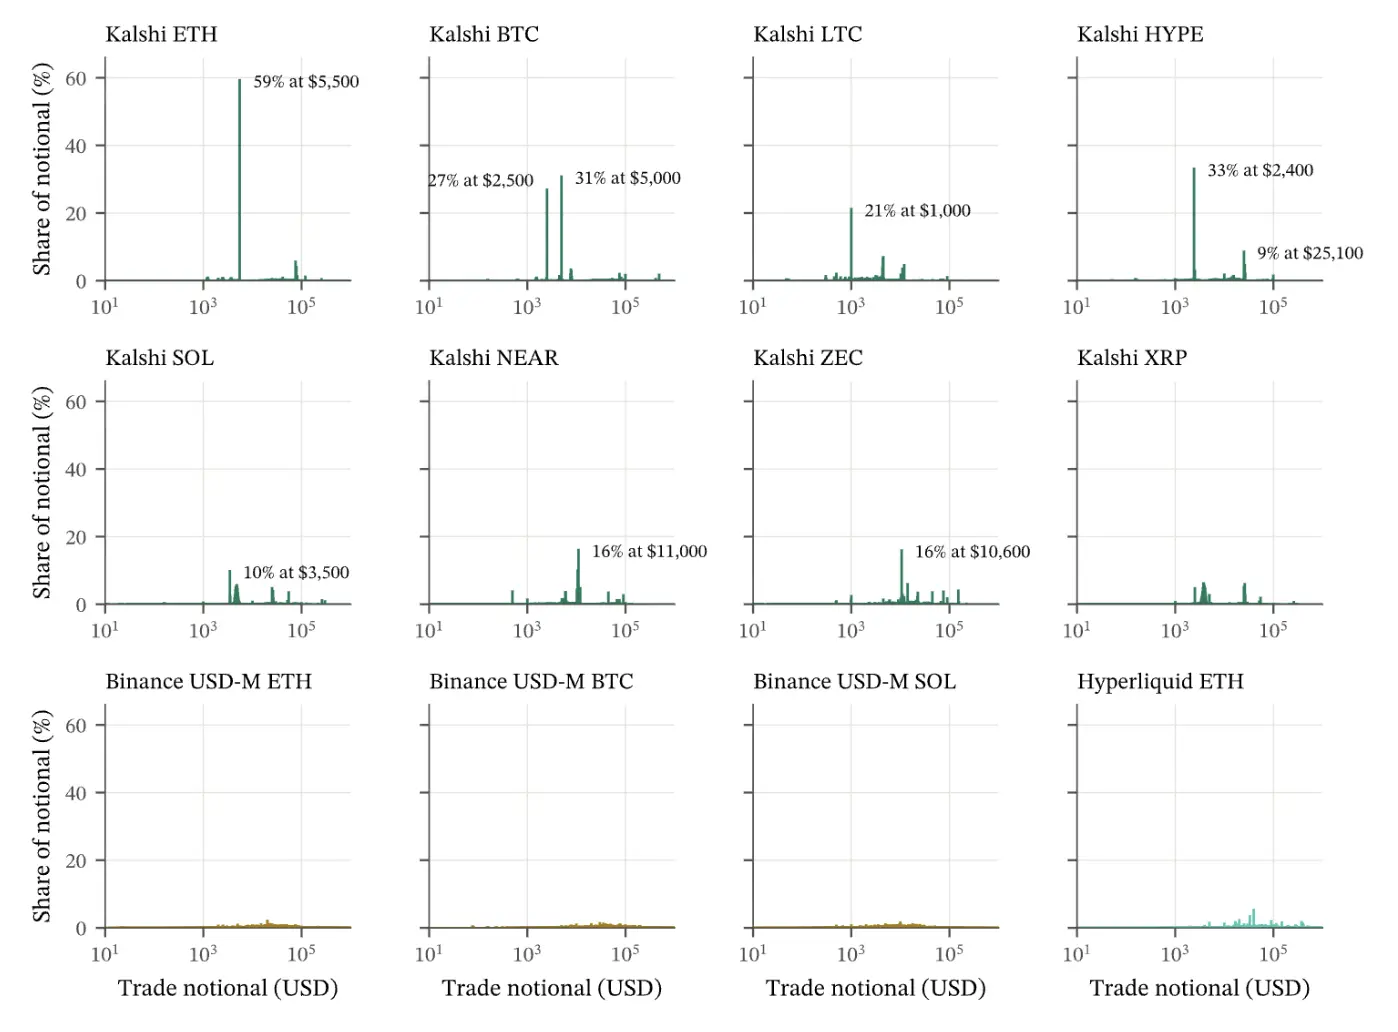
Source: OctopusTakopi, Paper Figure 3, Page 7. The horizontal axis represents the amount of each trade, and the vertical axis represents the proportion of the corresponding amount range to the total trading volume.
In the ETH market, orders around $5,500 contributed 59% of the trading volume. In the BTC market, orders around $5,000 and $2,500 together contributed about 57% of the trading volume. Just these three types of fixed amount orders accounted for about 51% of Kalshi's sample trading volume. It was known that the volume was fabricated, but it was surprising how rampant it had become.
Placing fixed amount orders is common; market-making and arbitrage programs may do this. The next question is, why does it account for more than half of an entire market's trading volume and change simultaneously across different markets?
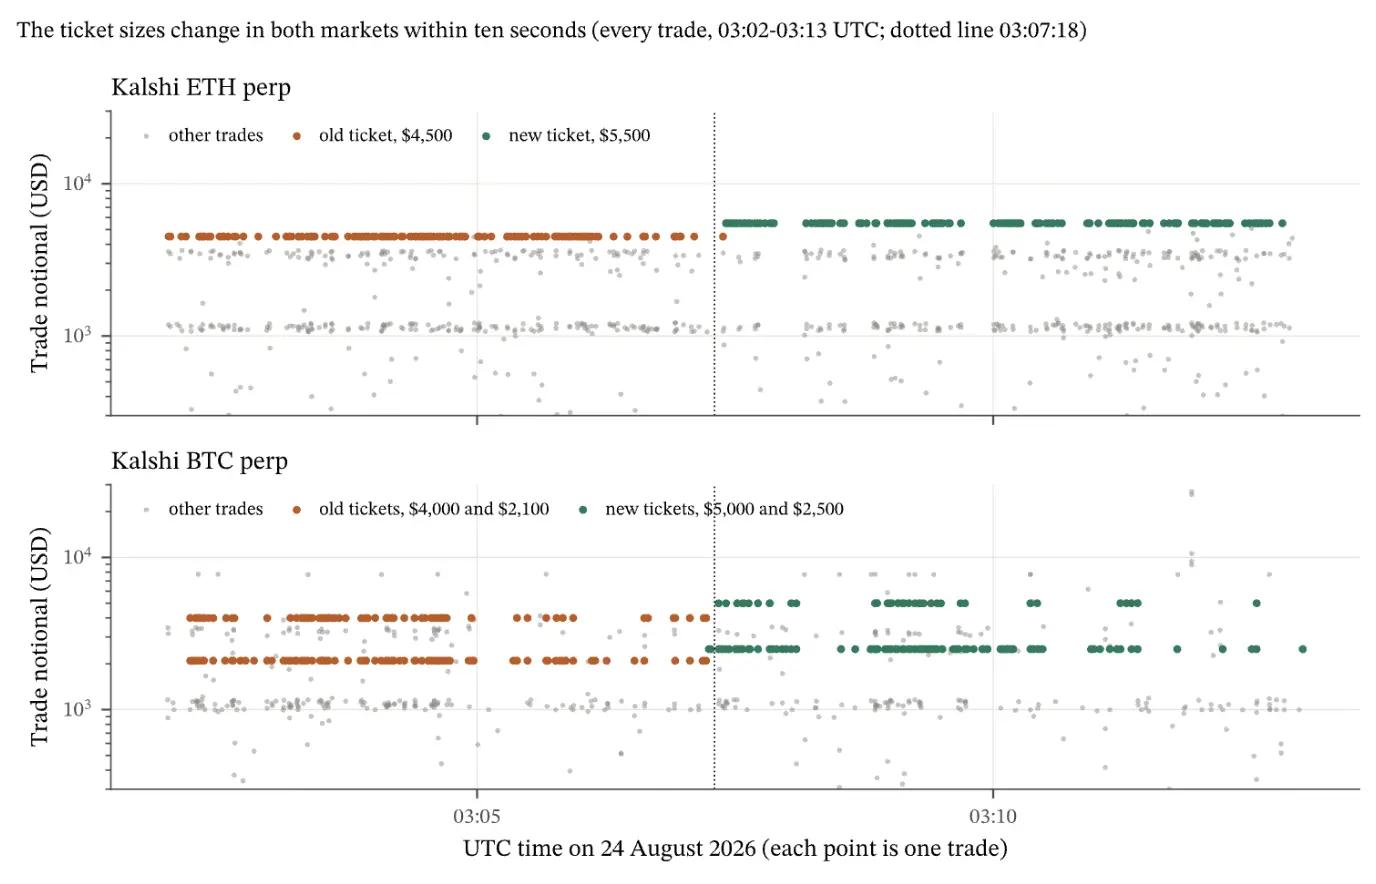
Source: Paper Figure 8, Page 12. Each point represents a trade, with orange representing old amounts and green representing new amounts.
On August 24, the fixed order amount for ETH changed from $4,500 to $5,500; the two groups of amounts for BTC changed from $4,000 and $2,100 to $5,000 and $2,500. The two markets completed the switch in about ten seconds. The orange horizontal line on the chart ended, and the green line appeared immediately.
This resembles a single operator modifying the parameters of the quoting program. Kalshi's team members thought that always placing $4,500 orders was a bit too fake, so they changed "4,500" in the code to "5,500." They even couldn't be bothered to change the program, opting for random numbers that are harder to detect.
The time intervals left another set of traces.
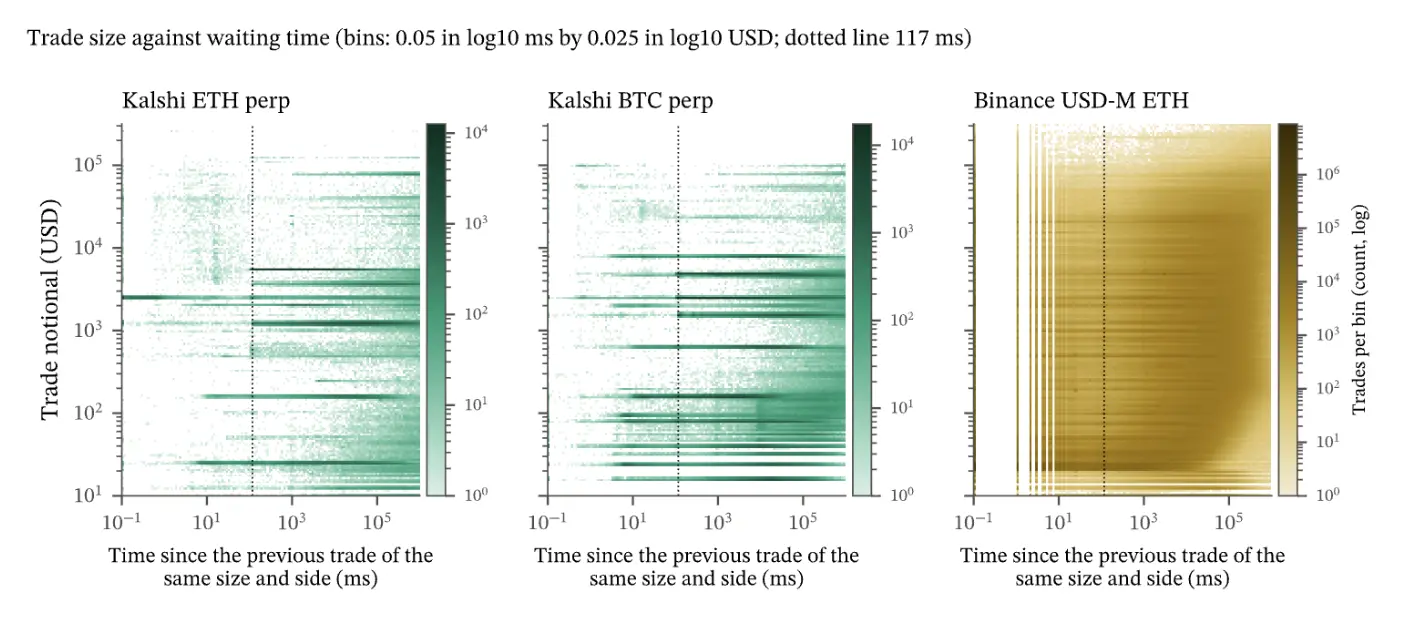
Source: Paper Figure 10, Page 14. The horizontal axis represents the time since the last trade of the same amount and direction, with the dashed line marking about 117 milliseconds.
In these fixed orders, consecutive trades in the same direction almost never had an interval of less than 117 milliseconds. The corresponding dark horizontal lines only began to appear near the dashed line. Trades of other amounts and the comparison samples from Binance did not have the same neat boundaries.
The paper explains that after a quote is filled, the program approximately needs this long to replenish the next one. It describes the time limit formed by the replenishment speed and should not be understood as the bot executing a trade every 117 milliseconds. However, when fixed amounts, synchronized parameter changes, and similar replenishment rhythms overlap, it becomes difficult to explain that "a large number of independent customers just happen to trade this way."
The trading volume corresponding to the open interest is also unusually low.
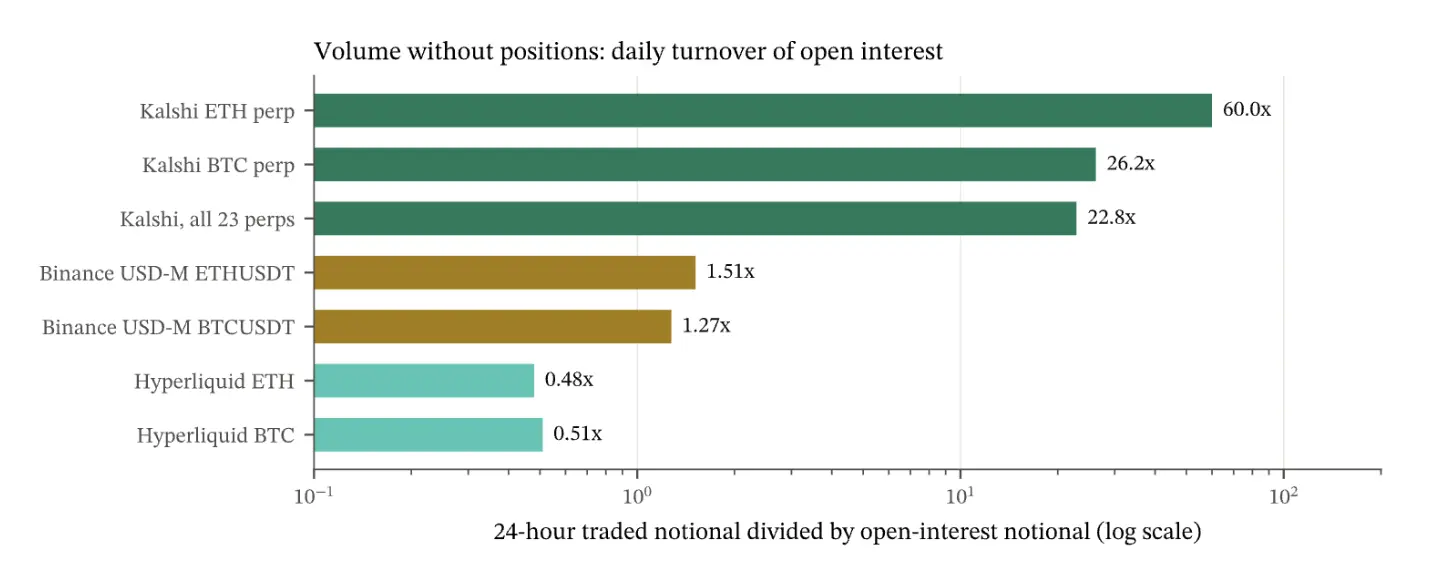
Source: Paper Figure 12, Page 15. Kalshi and Hyperliquid used snapshots from September 21, while Binance used the median daily values over two weeks; the horizontal axis is on a logarithmic scale.
Kalshi's daily ETH trading volume is equivalent to 60 times the open interest, while BTC is about 26 times, and all perpetual contracts are about 23 times. The corresponding values for BTC and ETH on Binance are about 1 to 2 times, while Hyperliquid is about 0.5 times. This echoes Beni's earlier observation of 174 times.
Logically, each trade of different amounts would increase or decrease the open interest, while only the hedging operations of opening long/short positions with the same amount would keep the open interest unchanged.
Therefore, among the 22 trades that occurred on Kalshi, the vast majority were simultaneous long/short hedging volume fabrication operations.
The paper also found that the fixed amount orders for ETH had a weak connection to external market conditions. The hourly trading volume of Kalshi had a correlation coefficient of only 0.19 with Binance's hourly ETH trading volume, while the correlation coefficient for Kalshi's other non-fixed amount ETH trades was 0.72.
In other words, the busyness of the market had a significantly smaller impact on this group of orders. The fixed orders for BTC did not show the same disconnection, so this point can only be applied to ETH.
These results collectively support a judgment: the trading volume of Kalshi's perpetual contracts heavily relies on a small number of mechanized trading flows.
The evidence is overwhelming; it is an undeniable fact that Kalshi is fabricating volume in its own contract market.
Has the Domino Effect Been Triggered?
Phenomena such as mismatched trading volume and open interest have been mentioned by industry insiders for a long time, but previously not enough people paid attention, so regulators did not have to bear pressure because of it. But perhaps this time is different.
Kalshi's political connections may invite more scrutiny as the controversy expands. If political opponents continue to trace this line, the company will need to address questions regarding both trading data and political relationships simultaneously.
In addition, market makers may also follow suit and withdraw. Beni cited reports of equity cooperation between Jump and Kalshi, questioning the incentive relationship between liquidity and platform valuation; if regulatory attention rises, Jump may reassess whether it is worth continuing to provide liquidity.
Even if a market maker believes its trading is fully compliant, responding to inquiries, reviewing strategies, and explaining business relationships will incur costs. If these costs exceed the benefits of cooperation, scaling down or exiting may become the best business choice.
The financing side will also encounter the same problem. When the actual transaction volume and fees cannot support the original growth expectations, the next round of financing may require longer due diligence, more stringent conditions, or even acceptance of lower valuations.
Everything is a cycle; overvalued DeFi protocols and large players manipulating TVL, PerpDEX using clumsy methods to inflate trading volume, and when the tide goes out, everyone is left exposed.
This time, can Kalshi fool the U.S. regulators with just a phrase "it's just business"?

