AI Burning Cash Too Fast? China's Wealthiest Tech Giants Scramble to Raise Funds
 Tapbit Wire
Several of China's richest internet companies have recently started seeking money externally.
Alibaba conducted a rights offering, Tencent issued bonds, and ByteDance secured a $29.6 billion syndicated loan from nearly 30 banks.
But the question is, do they really lack money? At least on paper, it doesn't seem that way at all.
As of the end of June this year, Alibaba still had 474.5 billion yuan in cash and other liquid investments. Tencent's officially reported "total cash" was also 511.2 billion yuan. ByteDance, which does not publish financial reports, is also one of China's most profitable internet companies.
Since they are already this wealthy, why are they still seeking money everywhere?
The answer is simple: AI.
The latest to join this financing wave is ByteDance.
On September 3, according to media reports, ByteDance initially planned to borrow only $20 billion. After the news was released, nearly 30 banks from China, the United States, Europe, and Singapore participated, with subscription amounts exceeding $30 billion. ByteDance subsequently expanded the loan scale to $29.6 billion, approximately 200 billion yuan, making it the second-largest dollar loan transaction in Asia this year.
What's more special is that such a large sum of money was obtained without collateral.
A person directly involved in the transaction stated that an unsecured loan of this magnitude is very rare. Simply put, the banks dared to lend the money based solely on ByteDance's own credit.
In 2024, ByteDance also borrowed $10.8 billion from about 20 domestic and foreign banks and other lending institutions. Now, the loan scale is nearly three times that of two years ago, yet the financing terms are even better.
What is the money for? ByteDance's explanation is "general corporate purposes," but according to media reports, this money will mainly be used to support the company's AI expansion.
Alibaba took a different path.
In late August this year, Alibaba placed new shares in Hong Kong, raising 80 billion Hong Kong dollars in one go, and stated its use very directly: all of this money will be invested in AI, primarily for expanding computing power, building large-scale AI data centers, and upgrading cloud infrastructure.
Tencent went to the bond market. In June this year, Tencent issued $2.45 billion and 15 billion yuan in bonds, with some of the yuan-denominated bonds directly maturing in 2056, a term of 30 years. Tencent did not say this money is specifically for AI investment, but at the same time, its investment in AI infrastructure has also significantly accelerated.
This phenomenon of big companies seeking money everywhere is not unique to China.
As of July 7 this year, Amazon, Alphabet, Meta, and Oracle had issued approximately $194 billion in bonds within the year, nearly 80% more than the $108 billion issued for the full year of 2025.
Among them, Meta issued $25 billion in bonds in a single offering at the end of April. Oracle plans to raise $45 billion to $50 billion this year through bonds and equity to supplement funding for its expanding cloud and AI infrastructure.
From China to the United States, more and more tech giants are starting to proactively seek external financing. It's not because they don't have money, but because AI is extremely capital-intensive.
If you go to Guangling County in Datong, Shanxi, and take a look at ByteDance's computing infrastructure, you might gain a more intuitive understanding of "AI burning money."
There, ByteDance's subsidiary Volcano Engine has deployed a large-scale Taihang Computing Center. For just the second phase, the total investment reaches 4.5 billion yuan, planning for over 15,000 server cabinets, and the second phase also includes supporting construction for a 220 kV power transmission and transformation project.
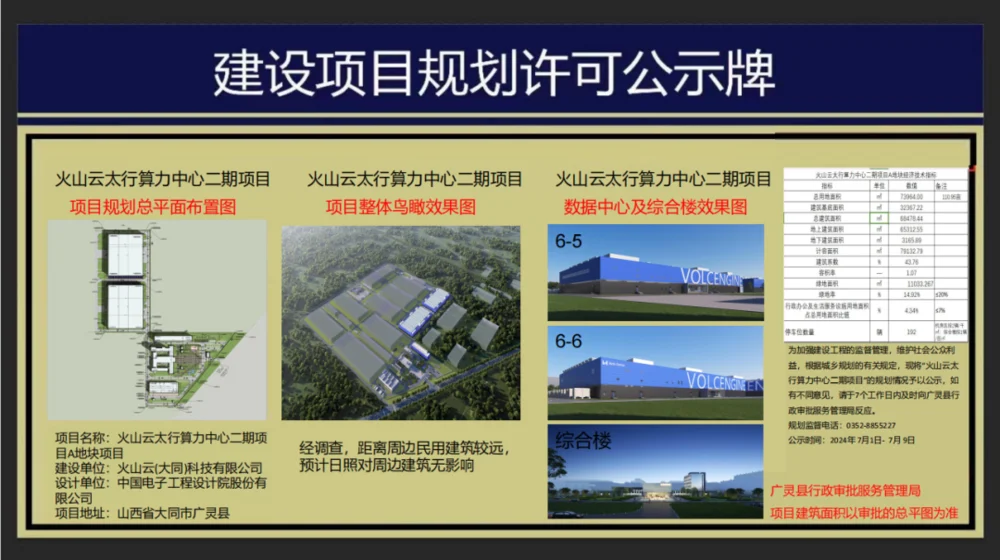
▲ Source: Guangling County People's Government Website
Usually, the AI we see is a chatbot, a video generated in seconds. But when it actually lands on the ground, it becomes buildings of server rooms, rows of servers, and a massive set of supporting infrastructure behind it.
Although chips usually get the most attention, obtaining the chips is just the first step. The real difficulty is how to turn individual chips into stable, operational computing power.
Since the beginning of this year, NVIDIA's H200 sales to China have gone through repeated approval and delivery processes. Even if a license is obtained, it doesn't mean the chips are available immediately. At the same time, data centers require time for construction, equipment deployment, and finally powering on.
This also means that investment in AI infrastructure is not only huge in scale but also requires advance planning and continuous investment.
As computing power demand continues to grow, the capital expenditures of big companies have also expanded rapidly.
At the beginning of 2025, Alibaba announced it would invest at least 380 billion yuan over the next three years to build AI and cloud computing infrastructure, spending about 67.7 billion yuan in the second quarter alone.
ByteDance is even more aggressive. According to media reports, ByteDance internally discussed increasing its 2026 capital expenditure to a maximum of $70 billion, equivalent to approximately 470 billion yuan, with the focus still on data centers and other AI infrastructure. This figure may ultimately be adjusted, but it sufficiently illustrates the scale of this race.
This sense of urgency is also evident in Zhang Yiming.
When announcing his resignation as ByteDance CEO in 2021, Zhang Yiming stated in an internal letter that he hoped to "take a ten-year horizon," spending more time learning, thinking systematically, and researching new things.
By July this year, he rarely spoke at an internal meeting of the Seed team, explicitly stating not to rely on distilling competitor models for short-term rankings, and expressed willingness to sacrifice some short-term gains for long-term goals.
In model R&D, Zhang Yiming still emphasizes long-termism, but in terms of computing power and infrastructure investment, ByteDance is clearly accelerating.
The reason is not complicated. If a model lags behind today, it can be iterated upon in six months. But if others have already installed a large number of GPUs in their server rooms and started operations, while your data center is still under construction and waiting for electricity, this time gap is very difficult to make up.
Moreover, in the AI era, infrastructure is no longer just a support behind the business; it is itself becoming a part of the business.
What a model can achieve, how many users it can serve, and whether costs can be reduced are all directly constrained by computing power. To some extent, where the infrastructure is built determines where the business's ceiling lies.
Therefore, the competition in AI may last for many years, but the race for infrastructure is concentrated in these few years. What big companies are truly competing for is not just chips, but also time.
But this brings up another question: since they have hundreds of billions in cash on their books, why don't they just spend their own money?
Because a company's money is never used for just one thing. Stock buybacks, acquisitions, and developing new businesses all require money, and room must be left for future risks and opportunities that may arise.
Servers, data centers, and other infrastructure generate value over many years. Using long-term funds to support long-term investments is a very natural choice.
Tencent is a very intuitive example. Although it hasn't specifically tied the bond proceeds to AI investment, long-term funds clearly leave more room for future large-scale investments.
Of course, there is another important prerequisite for big companies to dare to spend this way. The numbers are starting to add up.
During Tencent's second-quarter earnings call this year, an analyst asked a very direct question: If capital expenditure is calculated based on the approximately 53 billion yuan in the second quarter, the annualized capital expenditure would exceed 200 billion yuan. How would future depreciation and amortization affect profits? How long would it take for the new revenue generated by AI to cover these costs?
Tencent's Chief Strategy Officer, James Mitchell, revealed another layer of logic behind the company's capital expenditure.
According to him, given the current computing power demand and rental prices, if Tencent, like some emerging cloud computing companies, directly rented out the new computing power to third parties, it could almost immediately cover equipment depreciation and quickly achieve decent returns.
Tencent President Martin Lau then added another calculation: some computing power for which payments and orders were placed a few months ago could now be resold, potentially yielding a profit of over 30%.
This effectively provides a "safety cushion" for Tencent's AI capital expenditure: if its own AI business grows quickly, it uses the computing power itself; if external demand is stronger, it can also monetize it through cloud services.
Computing power is transforming from a pure cost into a productive asset that can generate revenue.
Alibaba has also started making similar calculations. In August this year, Alibaba Group CEO Eddie Wu stated during the earnings call that based on the current average gross margin of AI products, AI-related capital expenditure can be recouped in about three years. With improvements in gross margin and operational efficiency, this could potentially be shortened to 2.5 years, or even around 2 years in the future.
He also mentioned that the A100 chips Alibaba purchased in 2020, and even the V100 chips purchased in 2018, are still running at near full capacity, with actual service life far exceeding the theoretical depreciation period.
At the same time, revenue is starting to catch up. Alibaba's AI-related product revenue has achieved triple-digit growth for the 12th consecutive quarter, with annualized revenue exceeding 49.5 billion yuan. In the second quarter of this year, Kuaishou's Kling AI revenue also exceeded 850 million yuan.
These figures cannot yet prove that the hundreds of billions of yuan invested in AI have been fully recouped. But at least, big companies are no longer just relying on imagination to calculate AI's future. How much to invest, how long to recoup, and how much revenue can be generated – this calculation is becoming increasingly clear.
Thus, a new cycle begins to form: more computing power allows for training more models and serving more customers; as revenue grows, the company has more confidence to continue investing and finds it easier to secure the next round of funding.
Money becomes computing power, computing power drives business, and business supports the next round of investment.
But the direction of the capital market is also shifting.
In the first half of this year, capital was enthusiastic about AI in both China and the United States. However, entering the second half of the year, the market has become more cautious, with increasing attention on whether high valuations can be realized and how long it will take for massive investments to pay off.
This is also why Alibaba's HK$80 billion rights issue is noteworthy. Alibaba is not short of cash, yet it still chose to secure the funds now. ByteDance expanded its syndicated loan scale, and Tencent issued long-term bonds — similar considerations lie behind these moves as well.
For big tech companies, stocking up on ammunition for the next few years while money is still easy to obtain is clearly a safer bet than waiting to raise funds when they are truly needed.
Because these are far from the only companies that will need capital going forward. Platform companies, chip companies, cloud vendors, and large model companies all still need to continue increasing their investments. When everyone simultaneously requires tens or hundreds of billions of yuan in funding, capital itself could become a scarce resource.
These big tech firms are increasingly aware that this AI battle is different from the internet era. Technology determines whether you can get a seat at the table, but how deep your pockets are may determine how long you can stay at that table.