BlackRock: The Fed raises rates for the first time in years. What happens to stocks and bonds?
 Tapbit Wire
The original title: First Fed rate hike in years: What it may mean for investor portfolios
Original author: Kristy Akullian
Editor's note: The Federal Reserve raised interest rates again after several years.
At the September meeting, the Federal Reserve raised the target range for the federal funds rate by 25 basis points to 3.75%–4.00%. The background behind this decision is not complicated: inflation remains above target, energy prices are rising again, and the U.S. labor market has not yet shown obvious deterioration.
But for investors, the more important question is not "how much was raised this time," but rather: if the United States re-enters a high-interest-rate environment, how will stocks and bonds perform next?
Kristy Akullian, Head of Americas iShares Investment Strategy at BlackRock, gives an answer in her latest report that is not pessimistic. Historically, the first rate hike has not necessarily meant that stocks and bonds will fall; on the contrary, as long as the economy remains resilient and interest rate volatility stays manageable, investment opportunities can still emerge in a high-rate environment.
The following is a translation of the original text:
The Federal Reserve has started raising interest rates again.
In September, the Federal Reserve raised the target range for the federal funds rate by 25 basis points to 3.75%–4.00%, the first increase since July 2023.
BlackRock believes there are three main reasons behind this rate hike: overall inflation remains elevated, rising energy prices are pushing price pressures higher again, and the U.S. labor market remains resilient.
Therefore, the Federal Reserve still has room to continue suppressing inflation without having to immediately worry about a marked deterioration in the economy and employment.
But for the market, a more important question has already emerged: if interest rates rise again, will stocks and bonds necessarily fall?
BlackRock's answer is: not necessarily.
A rate hike does not mean stocks and bonds must fall
The market usually interprets rate hikes as negative.
The reason is simple. After interest rates rise, corporate financing costs increase, and stock valuations may come under pressure; at the same time, rising bond yields may also cause prices of existing bonds to fall.
But from historical data, the relationship between rate hikes and asset declines is not so direct.
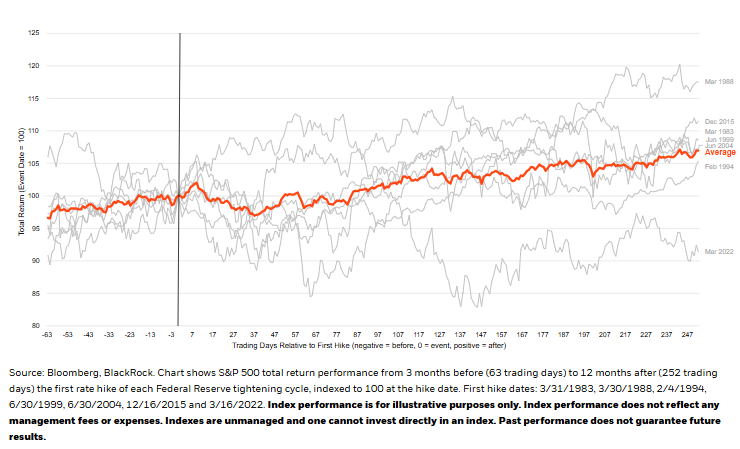
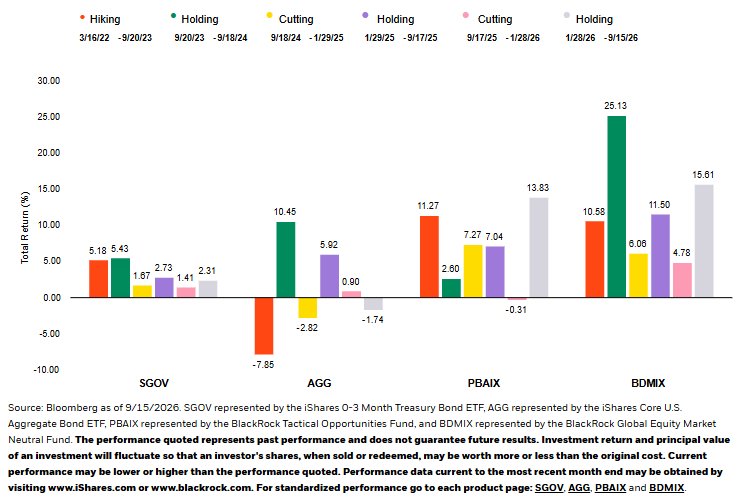
BlackRock analyzed seven Federal Reserve rate hike cycles since 1983. The results show that in the 12 months after the first rate hike, U.S. stocks rose by an average of 4.7%, U.S. bonds by an average of 3.07%, and high-yield bonds by an average of 4.68%.
Of course, this does not mean that "rate hikes are actually good for the market." More accurately, a single rate hike itself cannot determine the direction of asset prices over the next year.
The Federal Reserve usually raises rates when the economy is still relatively strong. If corporate earnings are still growing and the job market has not deteriorated significantly, then the economy's own growth momentum may offset some of the pressure from higher rates.
Therefore, rather than simply judging whether "rate hikes are bearish or bullish," the more important question is actually: Why is the Federal Reserve raising rates? And can the economy withstand higher rates?
For bonds, higher rates also mean higher yields
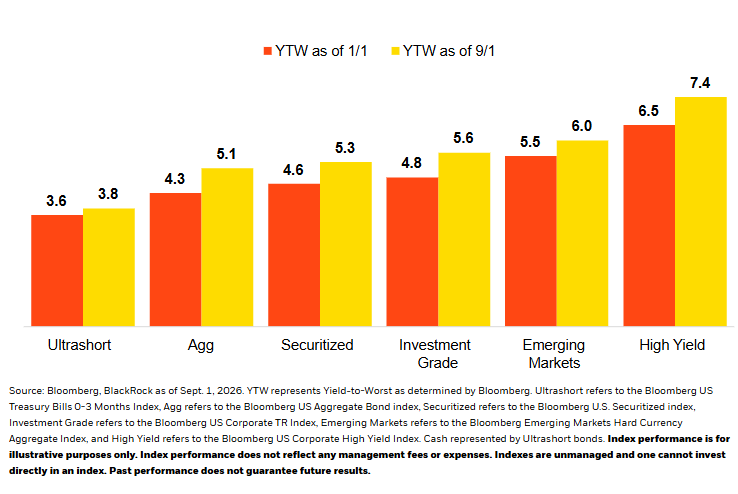
One of the biggest differences between this rate hike environment and previous years is that bonds themselves can already provide higher interest income. BlackRock believes that the currently higher risk-free rate and real yields provide a more attractive starting point for fixed-income assets.
In other words, although rising rates may压低 the prices of existing bonds, for investors preparing to buy new bonds, the yields they can obtain are also higher.
Therefore, higher rates are not purely bad news for bonds. BlackRock currently prefers bonds with higher credit quality, including investment-grade bonds and higher-quality high-yield bonds, while emphasizing obtaining returns through coupon income rather than overly betting on bond price increases.
However, the large issuance of U.S. Treasuries and corporate bonds may still push up long-term rates, so BlackRock believes that investors should not simply bet on a rapid decline in long-end rates at present, but need to manage bond duration more flexibly.
It is worth noting that long-term real yields are currently already at a relatively high level. BlackRock mentions that the real yield on 30-year U.S. Treasury Inflation-Protected Securities (TIPS) has exceeded 3%.
This means that even without relying on a large increase in bond prices, long-term bonds themselves are beginning to provide relatively considerable real returns.
What U.S. stocks truly fear may not necessarily be high interest rates
Compared with bonds, the problems facing stocks are somewhat more complex.
BlackRock remains relatively positive on U.S. stocks. Its reasoning is that U.S. corporate earnings are still strong, and historically stocks do not automatically enter a downtrend just because the Federal Reserve raises rates for the first time.
BlackRock data show that in the past seven rate-hike cycles, the S&P 500 still tended to rise overall in the 12 months after the first rate hike.
But there is a very important precondition here: interest rates cannot fluctuate violently. The market can actually gradually adapt to a higher but relatively stable interest rate environment. For example, if investors already believe that the policy rate will remain around 4% for some time in the future, then that level will eventually be gradually reflected in stock valuations and corporate financing costs.
The real trouble is that the market keeps reassessing how high rates will ultimately go. If inflation repeatedly exceeds expectations, investors keep raising their expectations for future rates, and long-term U.S. Treasury yields rise rapidly, then stock valuations also need to be constantly readjusted.
Therefore, what BlackRock really focuses on is not just whether rates are high, but whether rates will suddenly fluctuate sharply.
In this environment, BlackRock prefers large companies with higher earnings quality that can pay dividends steadily, while it is relatively cautious on small-cap stocks that are more sensitive to financing costs.
Buying stocks and bonds together may no longer diversify risk as it once did
Another thing that is changing is the relationship between stocks and bonds.
One important reason the traditional 60/40 portfolio became popular is that in the past stocks and bonds often hedged each other. When the economy worsened, stocks usually fell; but at the same time, the Federal Reserve might cut rates, bond prices would rise, and that would offset part of the stock losses. But in recent years, this relationship has become less stable.
According to data from BlackRock and Morningstar, from 2010 to 2019, the correlation coefficient between stocks and bonds was about -0.22; since 2020, this figure has risen to 0.51. That is, in recent years there have been more instances of stocks and bonds rising together or falling together.
The reason is that the main risk facing the market has changed.
If the market is most worried about an economic recession, bonds usually benefit when stocks fall. But if the market is most worried about inflation, the situation may be completely different: rising inflation pushes interest rates higher, bond prices fall, and at the same time higher interest rates also depress stock valuations.
This is also why BlackRock believes that the traditional "stocks + bonds" portfolio may no longer be as stable as it once was, and that other assets or strategies with different sources of return need to be added to further diversify risk.
Next, it is not just about whether the Fed will raise rates again
BlackRock's baseline judgment is that the Fed may raise rates one more time in 2026, but it does not currently believe this will develop into a very aggressive rate-hiking cycle.
For the market, what is truly worth watching next may not be "one more hike or two," but three more important variables.
The first is whether inflation will continue to rise.
If energy prices gradually fall back and inflation cools again, the pressure on the Fed to keep raising rates will decline; conversely, if inflation spreads further, the market may need to revise up its expectations for interest rates.
The second is whether the economy and corporate earnings can withstand high interest rates.
Historically, stocks have still risen after rate hikes, often when the economy has continued to grow. If employment, consumption, and corporate earnings all weaken significantly at the same time, then the reference value of past historical experience will also decline.
Finally, and most importantly in this BlackRock report: what truly needs to be guarded against may not be high interest rates, but interest rates suddenly becoming very unstable.
If the economy remains resilient and the market can gradually adapt to a higher but stable interest rate environment, then stocks may still rise, and bonds can also provide returns through higher coupons. But if inflation keeps fluctuating, causing the market to continually revise up rate expectations and long-term rates to surge rapidly, then both stocks and bonds may once again come under pressure.
Therefore, what really matters in this rate-hiking cycle is not just when the Fed will act next time. More importantly: whether high interest rates can remain stable, and how much longer the U.S. economy can withstand them.